Edit
Born of crisis: how the euro changed Bulgaria
From a currency board to the eurozone – three decades of discipline, missed reforms, and new risks for the economy and politics
Bulgaria’s path to the euro did not begin with a ceremonial event in Brussels. It began with a national catastrophe at home. The financial meltdown of 1996–1997 – hyperinflation, bank failures, evaporated savings, political chaos – didn’t just shake the country. It forced it to choose a new survival model. That was the moment the regime that would define Bulgaria’s economic and political trajectory for two decades was born: the currency board, the longest-lasting in Europe.
Introduced in 1997, the board first pegged the lev to the German mark and later to the euro at a fixed rate of €1 = 1.95583 levs. It stabilized the economy and restored trust in money, but it also placed Bulgaria under a peculiar regime: strict fiscal discipline, limited monetary sovereignty, and narrow room for political improvisation. The country gained stability – at the price of the freedom to make mistakes with impunity.
In February 1997, amid protests and political crisis, the 37th National Assembly adopted a declaration of national consensus locking in the country’s course toward the EU and NATO. That was more than a foreign policy formula – it was an admission that the collapse of the old model could not be fixed without an external anchor. If the currency board was the economic answer to the crisis, European integration became the political way out.
Nearly three decades later, with the euro now the national currency, the question is not just how Bulgaria got here. The more important question is how this transition – born of crisis – changed the state, its institutions, and its political class – and whether the lessons learned are enough for the next stage. Because eurozone membership is not a symbolic finish line. It is the beginning of a new development model, one for which politicians still lack clear answers.
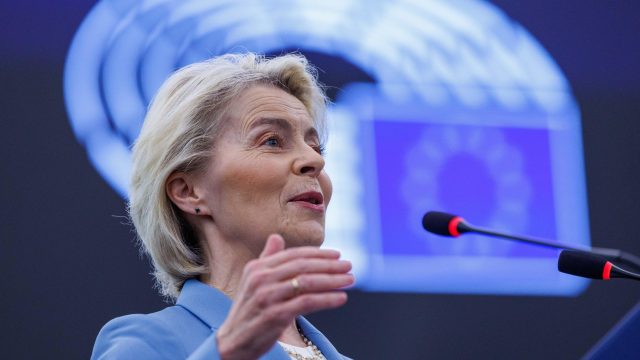
“The euro is a tangible symbol of European strength and unity […] And Bulgaria will take its rightful place in shaping the decisions at the heart of the euro area,” European Commission President Ursula von der Leyen said on the day Bulgaria received political confirmation that it was ready to become the eurozone’s 21st member.
Behind that symbolism, however, lies a harsh reality. Inside the eurozone, the country can no longer hide behind the automaticity of the currency board. From now on, real coordination between the Bulgarian National Bank (BNB) and the Ministry of Finance is essential. The central bank governor sits at the ECB’s table for interest rate and liquidity decisions; the finance minister joins the Eurogroup and the Ecofin Council. Without coherence between them, Bulgaria risks losing the most valuable thing it gained with the euro: trust.
This is especially critical for a country where the currency board long served as a safeguard. The board eliminated pressure on the central bank, healed public finances, and imposed a discipline that the political class could not enforce on its own.
But with eurozone accession, responsibility rises. Financial stability will now depend less on binding rules and more on politicians and institutions. Bulgaria’s democratic transition has shown that those in power are often tempted to break the rules.
1997: In the Shadow of the euro
The currency board was not the ideal regime – it was the rescue regime. Its effect was visible almost immediately. Inflation, which hit 1,058% in 1997, dropped to an average of 7.36% in 2001 – compared to 2.4% in the EU. The budget deficit of 6.3% of GDP at the end of 1997 shrank to 0.98% in 1999.
That predictability – a direct effect of the board – also had a psychological impact. Lyubomir Datsov, a member of the Fiscal Council and former deputy finance minister, emphasizes that the fixed exchange rate curbed speculation and smoothed the transition to the euro. According to him, the state had been consciously preparing for this process for two decades, including through the design of Bulgarian banknotes, which are being replaced ahead of the euro switch – designed to resemble euro banknotes.
Lyubomir Karimanski, a member of the BNB Governing Council, notes that the currency board imposed fiscal discipline, limited political impulses, and, due to the fixed rate, proved even more effective than the ERM II mechanism, which allows for fluctuations of ±15%. In his view, this allowed the focus to shift toward deeper institutional and financial convergence, particularly in banking supervision and regulation.
Dimitar Sabev, an economist at the Bulgarian Academy of Sciences’ Economic Institute, describes the euro as the sensible exit for Bulgaria. Removing the board without political good faith would have led to a severe crisis, he says. Still, he notes that the euro itself is an unfinished project – its biggest flaw being that “it is a common currency without a common fiscal policy.”
Sabev argues, however, that the board turned into a “golden corset” – constraining growth and contributing to mass emigration of active, adaptable people due to low incomes, low labor costs, and a restricted money supply. Even so, he is a moderate optimist. He expects a partial recovery through the return of Bulgarians from abroad – already 10,000–12,000 per year in recent years – and a shift of production to Bulgaria. “Europe has an interest in moving medium-tech manufacturing to Bulgaria – in defense, aerospace. High tech is not possible, because we lack the skilled labor,” he says.
Sabev stresses that, given the recent elections, the key now is for Bulgaria to have a pro-European government that knows what it wants.
The difficult lessons
For decades, Bulgaria sold itself as a cheap periphery. That model is now exhausted. The average monthly wage has reached €1,369. Labor and energy costs are rising. Foreign investors are pulling out. In recent years, foreign direct investment has hovered around 2.5–3% of GDP – far from pre-2008 levels, when it exceeded 20%. The country faces a labor shortage. Between 2019 and 2025, Bulgaria brought in over 130,000 foreign workers.
According to Karimanski, to attract investors without the advantage of low wages, Bulgaria must offer stability and predictability – including guaranteed legal certainty. He believes the eurozone can help, but what remains decisive is the quality of the domestic environment, including energy efficiency and investment levels. “Weak growth in gross fixed capital formation signals structural problems that deter investors,” he says.
The currency board stripped the BNB of the classic central bank function – conducting independent monetary policy – and deprived the executive of the ability to coordinate fiscal policy with it. In the eurozone, economic and monetary policy are inseparable, because decisions on inflation and stability depend simultaneously on budget policy, the real economy, and central bank actions.
Adopting the euro does not hide the weaknesses of Bulgarian politics – it sharpens them. Decisions directly impact the budget, the cost of debt, and market confidence, which watches fiscal discipline and political stability above all.
No sooner has Bulgaria entered the eurozone than it heads to elections – the eighth in five years. Rising uncertainty from the Middle East conflict is driving up energy commodity prices. The BNB forecasts annual inflation accelerating to 4% by the end of 2026.
Against this backdrop, BNB Governor Dimitar Radev warned that amid external uncertainty, domestic politics must be predictable and measures targeted and temporary. At an American Chamber of Commerce forum, caretaker Finance Minister Georgi Klisurski called for “optimization” of public spending in the future 2026 budget.
Risks remain: the extended 2025 budget, pressure for compensation, and pre-election populism all cast doubt on fiscal discipline. According to Karimanski, “a central bank governor needs absolutely unconventional tools to suppress the desire for fiscal indiscipline, for opening the purse under political pressure.” “Thank God for the currency board – it didn’t allow political fantasies to run wild, as we see now,” he says. “The BNB’s goal now is price stability through monetary policy.”
Datsov calls the board “the perfect killer – you make a mistake, and you pay for unreasonable policies.” He notes that consistent debt reduction to about 14% of GDP on the eve of EU membership created a buffer that still gives the economy flexibility. “Later, debt rose to around 28% of GDP, but it remains relatively low, allowing Bulgaria to be seen as low-risk when it chooses to finance itself on external markets.”
The currency of trust
The currency board stabilized the economy, but trust – key for investors – is built on the rule of law and functioning institutions, areas where Bulgaria continues to lag. “Corruption is not just a moral problem; it is a factor that undermines trust. Although Bulgaria received a credit rating upgrade following the eurozone accession decision, there has been no subsequent upgrade like that seen in other countries after joining – suggesting that trust remains fragile,” Karimanski notes.
Lyubomir Datsov finds the behavior of the political class problematic. “Investors judge the state through its institutions, and a weakened executive and lack of clear leadership undermine growth prospects,” he says. In that sense, the euro does not compensate for domestic weaknesses – it makes them more visible.
In recent years, the euro issue was pulled out of its economic context and turned into a tool for polarizing society. Amid intensified Russian hybrid operations, disinformation campaigns fueled fears of impoverishment, inflation, loss of sovereignty, and external control. These were actively spread by pro-Russian national-populist parties like Vazrazhdane and backed by allied political formations.
Even though Bulgaria is now in the eurozone, the euro continues to be used politically – both by Vazrazhdane and by former President Rumen Radev and his coalition “Progressive Bulgaria,” tipped as the winner of the 19 April elections. Their messaging ranges from claims of “falsified data” during accession to the argument that citizens were not consulted – despite a Constitutional Court ruling that a referendum could not be held. False suggestions even circulate that Bulgaria might leave the eurozone after April.
A study by Sensika Technologies recorded a peak in disinformation on the eve of euro adoption, dominated by conspiracy and geopolitical narratives.
Several shades of gray
Commercial banks played a key role in a relatively smooth euro transition, taking on the operational burden and accelerating the withdrawal of levs from circulation. According to Lyubomir Datsov, they invested an estimated over 500 million levs (€255.6 million) in eurozone preparations, modernizing the sector and strengthening controls. “For banks with Bulgarian owners, governance changes were also necessary – including a clearer separation between ownership and professional management. As a result, the sector today looks more mature and better regulated, and risks accumulated in recent years have been largely contained,” Datsov says.
The euro also contributed to a partial brightening of the economy, as significant amounts of cash – over 17.7 billion levs (€9.05 billion) – entered the banking system.
According to Datsov, “the gray sector in Bulgaria is not significantly larger than in other European countries – around 16–20% of the economy. The problem is its concentration in a few sectors – construction, agriculture, and some services – and its dependence on a limited circle of players, which makes it more of a political than a technical problem. In that sense, the euro may have a limited positive effect, but it does not fundamentally change the picture: the gray sector remains a structural problem and at times even functions as a buffer under economic pressure.”
However, Bulgaria remains on the FATF “gray list” for money laundering and has been under enhanced monitoring since 2023. The prosecution service is the only institution that has not yet met the requirements of the exit plan. Bulgaria has met 24 out of 25 criteria – the last one concerns the implementation of reforms in criminal prosecution of money laundering.
Last year, the ECB reminded Bulgaria that further anti-money laundering actions are needed.
According to Karimanski, clear rules and guidelines exist, including from the BNB, but coordination between institutions and the lack of reliable, well-organised data remain problems.
Since 2025, a new European Anti-Money Laundering Authority (AMLA) has been operating in Frankfurt, aimed at coordinating national structures to better counter these practices. Bulgaria’s financial intelligence unit, which operates within the State Agency for National Security (DANS), is supposed to send a representative to the AMLA committee – but so far there is no information on this selection process.
Nearly three decades after the introduction of the currency board, the legislative framework has improved, the BNB’s oversight has strengthened, and Bulgaria is an EU and NATO member. But the root causes that led to the currency board – corruption, a captured judiciary, and weak political governance – have not been fully overcome, and they continue to generate risks of future crises.
This article is part of the Bulgaria International Journalism Fellowship (BIJF), and implemented by AUBG’s Center for Information, Democracy, and Citizenship (CIDC).
Caption: A change office in the port city of Burgas doesn’t look very busy since the euro became Bulgaria’s currency [Photo: Georgi Gotev]
Updated: April 16, 2026 - 10:39